Showing posts with label banks. Show all posts
Showing posts with label banks. Show all posts
March 12, 2020
Richard Wolff: Banks Are Trembling!
September 13, 2019
The Last Time Banks Did This, They Caused a Financial Crash with Richard Wolff
The banks are supposed to hold a percentage of every dollar in reserves, which means they have a large pile of money. What happens if the government wants to stimulate the economy, by telling the banks they can lend out part of their held deposits or all of it? The last time the banks were able to lend out their reserves... we found ourselves in a global financial crash!
Dr. Richard Wolff explains to Thom how all this works.
December 01, 2018
The US Senate Has Left Us Vulnerable to the Big Bank Criminals
May 22, 2017
Brexit: Will UK Banks Move Abroad? - BBC Newsnight
December 27, 2013
'Soviet System in UK Where Banks & Politicians Control Our Lives'
October 27, 2012

The Rt Rev Justin Welby, Bishop of Durham, says the sector must be rebuilt “from the ruins” of the financial crisis to become something that “helps people rather than being there for people to help it”.
Bishop Welby, who is a member of the Parliamentary Commission on Banking Standards, called for the introduction of formal banking qualifications, for the Government only to only support financial institutions that have a “clear and explicit social value”, and to offer an easier tax regime and lighter regulation for banks that demonstrate a “social purpose”.
Speaking at a conference in Zurich, Switzerland, Bishop Welby said: “At the moment clearly these are merely ideas in the mist.
"But one principle seems to me to be clear, we cannot repair what was destroyed in 2008, we can only replace it with something that is dedicated to the support of human society, to the common good and to solidarity.
"Financial services are crucial to human development, but they only do their job when the work they carry out is done in a way that is truly a service." » | Graham Ruddick | Saturday, October 27, 2012
October 07, 2012
THE OBSERVER – EDITORIAL: He proposes that they should be kept on a short leash. It's a start, and will cheer Labour conference delegates
When Ed Miliband tells Labour conference delegates that he plans to break up Britain's banks should they backslide on tough new regulations, he is going further than the usual banker-bashing. When he attacks the government, which he argues has capitulated to intense lobbying and let the banks off the regulatory hook, it is not from the easy hit school of political point-scoring.
His strategy is broader and goes back to his long-held belief that a buccaneering, devil-take-the-hindmost approach to business is out of place in the 21st century. More than that, it is counterproductive and harmful to an economy that needs to shift away from a reliance on the money made by banks and their chief asset – the inflated loans made on seemingly irresistible property speculation.
Miliband may seem an awkward, even alien performer to some , but he will strengthen his appeal if he can stitch together policies that resonate with an audience that has spent the last four years watching incredulously as the City and the wealthy successfully defend their corner. Responsible capitalism sounds dull and un-British, but it also presents an opportunity for a little reinvention and a greater degree of fairness. It also has the potential to enthuse disenchanted Liberal Democrats as much as it does delegates desperate for some policy meat from the podium.
At the moment, we are going backwards, with income inequality getting worse and austerity leaving the wealthy unscathed. The crimes of the banks are many and well documented. They stretch from the branches and call centres that mis-sold payment protection insurance to the trading rooms that fiddled industry-wide interest rates and the boardrooms, where characters such as Barclays' boss Bob Diamond sanctioned aggressive tax-avoidance schemes. Not to mention the drug-running and money-laundering schemes that went on under the noses of HSBC and Standard Chartered and for which they have paid multibillion pound fines. Yet their lobbying power remains undiminished. » | Editorial | Saturday, September 29, 2012
May 19, 2012

The final wake-up call came from Moody's. On Thursday evening, the US rating agency downgraded 16 Spanish banks in one fell swoop, some of them by three notches. On Monday, the agency had already downgraded 26 Italian banks -- including major institutions such as UniCredit and Intesa Sanpaolo. The outlook for all the institutions involved is negative, Moody's said.
These are drastic steps, but they are hardly excessive. The European sovereign debt crisis long ago also became a banking crisis. The fate of the affected countries can not be separated from that of their financial institutions: If a state goes bankrupt, its banks too will struggle to survive. On the other hand, the examples of Ireland and Spain show that a shaky banking system can quickly overwhelm national budgets.
Moody's justified its downgrades of Spanish banks with the argument that the ability of the government to support individual banks has worsened. On Friday, the Spanish central bank was also forced to admit that the proportion of bad loans on the books of Spanish banks has risen to an 18-year high. According to the central bank, the share of bad loans rose in March to 8.36 percent, compared to 8.15 percent in the previous month. » | Stefan Kaiser | Friday, May 18, 2012
February 29, 2012

The Governor was angered by a comment from Andrew Large, a Labour MP on the Treasury Select Committee, who accused him of being “relaxed” about the current economic situation.
In a remarkable outburst in front of the committee he said he was "far from relaxed or complacent".
"I am actually rather concerned about it. I want to see something that makes sense economically, not something which is just a gesture."
Sir Mervyn said he had been "consistently and publicly" dissatisfied with what has been done.
"I said to the pervious government that the scale of the recapitalisation of the banks was inadequate and their actions in making sure banks lend to SMEs was also inadequate. I made that very clear."
The Governor then proceeded attack the current behaviour of banks – suggesting they are even trying to profit at taxpayers’ expense. » | Telegraph Staff | Wednesday, February 29, 2012
September 14, 2011
REUTERS: Moody's cut the credit ratings of two French banks on Wednesday because of their exposure to Greece's debt, highlighting growing risks to Europe's financial sector from a deepening euro zone sovereign debt crisis.
But the euro and European stocks were lifted by an announcement by the head of the European Commission that it would soon present options for issuing a common euro zone bond, despite huge political hurdles especially in Germany.
The ratings agency's one-notch downgrade of Societe Generale and Credit Agricole came hours before the leaders of Greece, France and Germany were to hold a video conference on measures to head off a potential Greek default, which has prompted rising global alarm. » | Lionel Laurent and Luke Baker | PARIS/BRUSSELS | Wednesday, September 14, 2011
January 11, 2011
THE DAILY TELEGRAPH: Bob Diamond, Barclays' chief executive, has told a committeee of MPs that badly-run banks should not be bailed out by taxpayers.
"It is not acceptable for taxpayers to bail out banks," Mr Diamond said during questioning by the Treasury Select Committee. He added that "badly managed" banks should be allowed to fail. >>> Louise Armitstead, and Amy Wilson | Tuesday, January 11, 2011
August 12, 2010

THE TELEGRAPH: Germany's Deutsche Bank and US investment bank Morgan Stanley are facing a $5m lawsuit led by a group of Irish nuns.
No banker is likely to risk describing what they do as "God's work", but they might hope at least not to get on the wrong side of His earthly followers.
Unlucky then for Germany's Deutsche Bank and US investment bank Morgan Stanley, who are facing a $5m (£3.2m) lawsuit led by a group of Irish nuns.
The Sisters of Charity of Jesus and Mary, the Holy Faith Sisters and the Irish Veterinary Benevolent Fund are among a group of 88 Irish individuals suing the two banks.
The nuns allege the two banks profited at their expense by failing to redeem an investment linked to the debt of German financial group Dresdner Bank and in so doing cost them millions of pounds. >>> Harry Wilson, Financial Services Correspondent | Wednesday, August 11, 2010
January 14, 2009
THE GUARDIAN: Global poll shows UK least likely to trust politicians, banks or markets
British economic confidence has been shattered by the financial crisis, according to a unique international poll published today. It shows that people here are now less likely to trust banks, the stockmarket or the government's economic management than people in comparable nations.
The research, carried out by WIN, an international network of pollsters including ICM in Britain, used professional polling techniques to assess public opinion in 17 countries, including the major G8 economies as well as China and India.
On most measures, British people emerged as among the most pessimistic of the 14,555 people questioned around the world.
Remarkably, confidence in the banking system appears lower in Britain - 4.2 out of 10 - than in bankrupt Iceland, which polled 4.6.
While around a third of citizens in developing economies such as India and China say the economic situation in their countries could improve in coming months, more than three-quarters of people in Britain expect it to worsen.
Pessimism here is slightly deeper than in competitors such as France, Spain and Germany, and equal to Japan. >>> Julian Glover | Wednesday, January 14, 2009
Listen to audio: Economy poll: 'Where Americans are pretty positive, in Britain trust is really low': Julian Glover reports that a world poll shows that Britons are among the gloomiest about the economy >>> Julian Glover | Wednesday, January 14, 2009
The Dawning of a New Dark Age (Paperback & Hardback) – Free delivery >>>
November 09, 2008
THE SUNDAY TIMES: High Street banks have told Alistair Darling they will not pass on any further interest rate cuts to consumers and businesses.
The banks have warned the chancellor they are “not charities”. They said they could not afford further to reduce mortgage payments and interest rates to businesses if, as expected, the Bank of England continued to cut rates as the economy fell deeper into recession.
The tough line from the banks will anger taxpayers, coming just a month after the government injected £37 billion into Royal Bank of Scotland (RBS), HBOS and Lloyds TSB to protect them from the credit crunch. Northern Rock and Bradford & Bingley have already been rescued by the taxpayer.
Most main banks have responded to the 1.5 percentage point cut made by the Bank of England on Thursday. The only two big lenders not to have trimmed their rates are HSBC and Barclays, which both avoided the Treasury-backed bailout.
Bankers, who were summoned to a meeting at the Treasury on Friday morning, have told Darling that these latest cuts, which took bank rates to a 54-year low at 3%, represented a “line in the sand”.
“Base rates are now so low that our margins are desperately small,” said one bank executive. “This point was made quite clear to the chancellor by several of the executives — we are not charities.” >>> Robert Watts and Iain Dey | November 9, 2008
The Dawning of a New Dark Age (Paperback & Hardback) – Free delivery >>>
February 20, 2008
SPIEGELONLINE INTERNATIONAL: The German government has had to bail out state-owned banks with taxpayers' money after their managements recklessly gambled away billions on subprime investments. But if a state-owned bank were to go under, the consequences could be disastrous for the whole economy.
Ingrid Matthäus-Maier, a member of the center-left Social Democratic Party (SPD) and the CEO of the state-owned KfW banking group, is undoubtedly in one of Germany's highest earnings brackets. Although her annual salary of €418,000 ($614,000) is substantially lower than that of her counterpart at Deutsche Bank, Josef Ackermann, who earns a tidy €13 million a year, she does earn more than twice the salary of German Chancellor Angela Merkel, who has to make do with a mere €200,000.
That's nice for Matthäus-Maier. A lawyer by profession who was a financial expert for the SPD for many years, she would not have been able to get on the board of a private bank in 1999, the year she joined the board of KfW -- she lacked the banking experience required by law. But KfW is not subject to the same regulations as other banks, which explains why Matthäus-Maier doesn't owe government auditors an explanation -- not even now, in the wake of recent public accusations that she botched the IKB crisis.
As the head of KfW, Matthäus-Maier is a major shareholder in IKB, the Düsseldorf-based bank that is on the brink of bankruptcy and is only being kept afloat by a series of government bailouts running into the billions (more...). Last week was marked by one crisis meeting after the next, but the headstrong government banker had more than the future of IKB on her mind. Indeed, she seemed more concerned about her employment contract and whether it would be extended. Her demands triggered an irritated reaction from the head of the KfW supervisory board, Economics Minister Michael Glos, as well as from others present at the meetings. Two days later, it was announced… >>> By Wolfgang Reuter
Mark Alexander (Paperback)

Mark Alexander (Hardback)
February 07, 2008
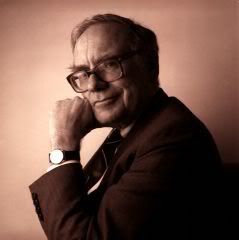
BUSINESS TELEGRAPH: Billionaire Warren Buffett has accused major investment banks of creating their own downfalls through the collapse in the US sub-prime mortgage market.
Mr Buffett, known as the "Sage of Omaha" for his investment record, suggested that the banking fraternity has only itself to blame for its recent problems which have seen banks write off more than $130bn (£66.3bn) so far.
"It's sort of a little poetic justice, in that the people that brewed this toxic Kool-Aid found themselves drinking a lot of it in the end," Mr Buffett said, making reference to the American soft drink.
The septuagenarian investor, speaking in Toronto, said that in spite of the meltdown in the sub-prime mortgage market and the impact on the banking system, funds remain available.
"I wouldn't quite call it a credit crunch," he said. "Money is available, and it's really quite cheap because of the lowering of rates that has taken place."
However, he said what had taken place was "a re-pricing of risk," leading to an "unavailability of what I might call 'dumb money', of which there was plenty around a year ago."
Mr Buffett also reiterated his negative views on the subject of the US dollar, saying that over the next five-10 years, the dollar could seriously devalue if the US trade deficit persists. As a result, Mr Buffett - who famously bet $21.8bn against the dollar in 2005, a position he has since unwound - stressed he will continue to look beyond the US for investments in part to hedge against the dollar's weakness. Warren Buffett blames banks for meltdown >>> By James Quinn Wall Street Correspondent
Mark Alexander (Paperback)
Mark Alexander (Hardback)
January 25, 2008
GLOBE AND MAIL: It seems only yesterday that Premier Dalton McGuinty declared: "There will be no sharia law in Ontario." Many of us, who witnessed the medieval nature of manmade sharia laws in our countries of birth, heaved a sigh of relief back in September of 2005. We thought this was the end of the attempt by Islamists to sneak sharia into a Western jurisdiction. We were wrong.
The campaign to introduce sharia is back. Last time, the campaign took a populist approach, invoking multiculturalism. This time, the pro-sharia lobby is dangling the carrot of new niche markets and has the backing of Canada's major banks. Such icons of the corporate world as Citibank NA, HSBC Holdings PLC, and Barclays PLC have endorsed sharia banking and have started offering Islamic financing products to a vulnerable Muslim population.
In May, 2007, The Globe reported that "Several Canadian financial institutions are preparing sharia-compliant mortgages, insurance, taxi licensing and investment funds to help serve the country's fastest-growing part of the population." Recently, the Toronto Star's business section reported that an unnamed bank may offer sharia loans as early as this summer; Le Journal de Montreal disclosed that Canada Mortgage and Housing Corporation (CMHC) was also getting in on the act. Stephanie Rubec, spokesperson for the CMHC, said the Crown corporation had launched a tender worth $100,000 to study Islamic mortgages for Muslim Canadians. Could she be oblivious to the fact that almost all Muslim Canadians currently have home mortgages through banks and don't feel they are living in sin? In fact, CMHC has gone a step further: It has quietly entered into a partnership with a Saudi company, AaYaan Holdings, to develop sharia-compliant mortgage-lending systems.
The origin of Islamic banking has its roots in the 1920s, but did not start until the late 1970s and owes much of its foundation to the Islamist doctrine of two people — Abul Ala Maudoodi of the Jamaat-e-Islami in Pakistan and Hassan al-Banna of the Muslim Brotherhood in Egypt. The theory was put into practice by Pakistani dictator General Zia-ul-Haq who established sharia banking law in Pakistan.
Proponents of sharia banking rest their case on many verses of the Holy Koran that outlaw usury*, not interest.
Verses that address the question of loans and debts include:
Al Baqarah (2:275): God hath permitted trade and forbidden usury;
Al Baqarah (2:276): Allah does not bless usury, and He causes charitable deeds to prosper, and Allah does not love any ungrateful sinner.
Every English-language translation of the Koran has translated the Arabic word riba as usury, not interest. Yet, Islamists have deliberately portrayed bank interest as usury and labelled the current banking system as un-Islamic. Instead, these Islamists have created exotic products with names that are foreign to much of the world's Muslim population. This is where they mask interest under the niqab of Mudraba, Musharaka, Murabaha, and Ijara. Two authors, both senior Muslim bankers, have written scathing critiques of sharia banking, one labelling the practice as nothing more than "deception," with the other suggesting the entire exercise was "a convenient pretext for advancing broad Islamic objectives and for lining the pockets of religious officials." Why Canadian banks would contribute to this masquerade is a question for ordinary Canadians to ask. Banks are helping sharia make a back-door entrance >>> By Tarek Fatah
*Usury is “the practice of lending money at exorbitant, or illegally high, rates of interest”. [Source: Dictionary.com]
Tarek Fatah is the author of Chasing a Mirage: The Tragic Illusion of an Islamic State, to be published in March.
Mark Alexander (Paperback)
Mark Alexander (Hardback)
Subscribe to:
Posts (Atom)