July 25, 2011

Democrats and Republicans are locked into a dangerous game of seeing who will crack first over the national debt crisis, with the White House warning that the next few days could be stressful for world markets and Americans.
With time running out, congressional leaders from both sides met on Saturday after the dramatic collapse of negotiations between Barack Obama and the house Republican leader, John Boehner, on Friday. But the congressional talks broke up late on Saturday night after failing to make progress.
The White House chief of staff, Bill Daley, interviewed on Sunday on CBS, predicted that the next few days will be tense. "In the end, we may have a few stressful days coming up – stressful for the markets of the world and the American people."
In an effort to reassure markets reopening after the weekend, he claimed he was confident a deal would be reached before the 2 August deadline. The White House refused to discuss what contingency planning is taking place in the event no compromise. » | Ewen MacAskill in Washington | Sunday, July 24, 2011
July 16, 2011

On one side of the Atlantic, the eurozone debt crisis has spread to the countries that may be too big to save - Spain and Italy - though RBS thinks a €3.5 trillion rescue fund would ensure survival of Europe's currency union.
On the other side, the recovery has sputtered out and the printing presses are being oiled again. Brinkmanship between the Congress and the White House over the US debt ceiling has compelled Moody's to warn of a "very small but rising risk" that the world's paramount power may default within two weeks. "The unthinkable is now thinkable," said Ross Norman, director of thebulliondesk.com.
Fed chair Ben Bernanke confessed to Congress that growth has failed to gain traction. "Deflationary risks might re-emerge, implying a need for additional policy support," he said.
The bar to QE3 - yet more bond purchases - is even lower than markets had thought. The new intake of hard-money men on the voting committee has not shifted Fed thinking, despite global anger at dollar debasement under QE2.
Fuelling the blaze, the emerging powers of Asia are almost all running uber-loose monetary policies. Most have negative real interest rates that push citizens out of bank accounts and into gold, or property. China is an arch-inflater. Prices are rising at 6.4pc, yet the one-year deposit rate is just 3.5pc. India's central bank is far behind the curve. Continue reading and comment » | Ambrose Evans-Pritchard | Thursday, July 14, 2011
July 04, 2011

July 03, 2011

David Cameron has been warned by one of his most trusted cabinet ministers that his welfare policies risk making 40,000 families homeless.
The extraordinary claim, in a letter to the prime minister from the office of Eric Pickles, the communities secretary, exposes deep splits at the heart of government over plans to cap benefit at £500 a week per family.
The letter, leaked to the Observer, reveals Pickles's belief that the cap – announced with great fanfare at last year's Tory conference – will increase the burden on taxpayers, because thousands of families will be unable to pay their rent and will have to seek local government help. It blows apart the government's public insistence that a limit on benefit payments will have little impact on homelessness and child poverty. » | Daniel Boffey and Toby Helm | Saturday, July 02, 2011
June 30, 2011

NZZ ONLINE: Der Franken wird immer stärker. Schweizer Exportfirmen warnen vor dramatischen Folgen. Allen Horrorszenarien zum Trotz wächst die Schweizer Wirtschaft in einem erstaunlichen Tempo. Selbst die Exportbranchen legen zu – ein bemerkenswertes Paradox.
Der Schweizer Franken kennt offenbar keine Grenze nach oben. Seit Anfang 2010 hat der Euro gegenüber der Schweizer Währung über 18 Prozent verloren, seit Ende 2007 sogar rund 30 Prozent. Inzwischen ist der Euro für einen Preis von etwa 1.20 Franken zu haben. Selbst die leichte Entspannung der Lage in Griechenland ändert nur wenig an den Tiefstkursen der Gemeinschaftswährung.
Ein starker Franken verteuert die Exporte der Schweizer Firmen ins Ausland. Sie werden durch die hohen Preise gegenüber der ausländischen Konkurrenz benachteiligt. Historisch hatte das meist erhebliche Folgen für den Werkplatz. Beispielsweise hatte eine ähnliche Aufwertung des Frankens gegenüber der damaligen D-Mark von über 25 Prozent zwischen April 1977 und September 1978 die Wachstumsdynamik empfindlich belastet. Aufgrund solcher Erfahrungen wäre eigentlich zu erwarten, dass die Schweizer Exporte jetzt um rund 15 Prozent schrumpfen sollten.
Doch in der Realität ist es umgekehrt. Die Schweizer Wirtschaft wächst weiter in hohem Tempo und auch die Exporte halten sich erstaunlich robust. Dies überrascht offenbar selbst die Ökonomen des Bundes, hat doch das Seco Mitte Juni die Schätzung für das Exportwachstum im laufenden Jahr nochmals nach oben angepasst. Erwartet wird nun eine Zunahme der Exporte im laufenden Jahr um 4,6 Prozent. » | tsf | Donnerstag 30. Juni 2011
Are we reliving the 1930s or the 1970s? Looking at the catastrophe which has befallen Greece, it’s beginning to seem more like the former. The economic upheaval of the 1970s was pretty awful at the time, but ultimately, Western economies worked their way through the decade’s inflationary challenges to enter an unprecedented period of prosperity and economic advancement.
It’s much less easy to be optimistic about the outcome of today’s uniquely complex mix of economic conditions. Admittedly, there is as yet no comparison with the social deprivations of the 1930s, but even so, the inability of many countries to raise themselves out of their post-bubble slump makes comparisons with the pre-war era hard to avoid.
Everything up to and including the kitchen sink has been chucked at the problem, but still we are struggling to achieve escape velocity. Both in terms of fiscal and monetary measures, policymakers are all out of ammo.
The point has not been lost on the Bank for International Settlements (BIS) – often referred to as the central bankers’ bank. In its annual report this week, it draws the opposite conclusion to the one you might expect. If this were a 1930s-style slump, you might expect the BIS to support the present policy mix of ultra-loose monetary and fiscal measures. Instead, it sees this more as part of the problem than the solution. “The sooner advanced economies abandon the leverage-led growth that precipitated the great recession, the sooner they will shed the destabilising debt accumulated during the last decade and return to sustainable growth,” it says. “The time for public and private consolidation is now.”
Much the same strictures are aimed at the Bank of England, whose tolerance of relatively high inflation in pursuit of increasingly elusive growth is regarded by the BIS as dangerous and, if sustained, likely to trigger the kind of super-inflation seen in the 1970s. Continue reading and comment » | Jeremy Warner | Wednesday, June 29, 2011
June 29, 2011
THE GUARDIAN: Thorntons joins growing list of casualties in a week of retail misery that could cost 10,000 jobs
More than 10,000 retail jobs face the axe as the British high street faces one of its most painful bouts of contraction since the second world war amid the biggest squeeze on household budgets for decades.
As the government's austerity measures take hold, experts warned that the number of retailers going bust would continue to rise this year with a number of household names facing insolvency.
The confectioner Thorntons emerged as the latest high street casualty when it said on Tuesday it would close up to 180 stores, putting more than 1,000 jobs at risk. The flooring chain Carpetright followed suit, saying 50 stores could close as consumers shun purchases amid fuel and food price inflation and rising job insecurity, especially in the public sector.
Over the last week, a clutch of high street names announced they were in trouble. Habitat was among several to call in the administrators, putting 750 jobs on the line. The electronics retailer Comet is also shutting stores.
The department store chain TJ Hughes said it was planning to appoint an administrator after a slump in sales, raising a question mark over the future of 4,000 employees who work at its 58 stores in England and Wales.
The retail carnage will intensify the debate around the coalition's spending cuts and, on Thursday, 750,000 teachers and civil servants hold a one-day strike to protest at reforms to pay and pensions which they claim will leave them worse off despite having to pay more to into their retirement plans. In parliament, Labour is lobbying for a cut in VAT payments to bring relief to consumers and cushion shops from spiralling rent bills. » | Richard Wachman | Tuesday, June 28, 2011
THE GUARDIAN: High street slump: The 'dismal science' of a rebalancing economy: Even prosperous towns are tightening their belts – and that means disaster for retailers » | Michael White in Crawley | Tuesday, June 28, 2011
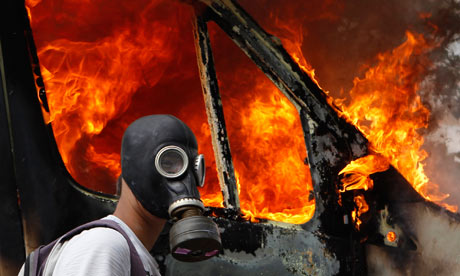
While Greece erupted in protest again, representatives of the country's government were at Claridge's hotel trying to drum up international investors' interest in a "fire sale" of its national assets.
Up for sale are 39 airports, 850 ports, railways, motorways, sewage works, a couple of energy companies, banks, defence groups, thousands of acres of land for development, casinos and Greece's national lottery. George Christodoulakis, Greece's special secretary for asset restructuring and privatisations, said the sell-off would raise €50bn (£44bn) to help pay back the country's €110bn bailout debt.
The private equity bosses gathered in the hotel's ballroom for the parade of Greece's national treasures showed little interest in buying anything.
Nikos Stathopoulous, managing partner of BC Partners, which has invested more than €3.5bn in Greece, said investors are put off by bureaucracy, strong unions, corruption and a lack of transparency. "Even in the good times Greece is not a country that attracts investment. Foreign investors don't want to invest in a country where there is no flexibility in hiring and firing people," he said. "You don't want to invest in a country in which you wake up and a new law has been passed which totally undermines and destroys the value of the investment you've just made." » | Rupert Neate | Tuesday, June 28, 2011
June 28, 2011
THE DAILY TELEGRAPH: Greek police fired tear gas at demonstrators in central Athens at the start of a 48-hour strike to protest austerity measures demanded by international lenders as the price for more financial aid.
As Greece teeters on the edge of bankruptcy, parliament is due to vote this week on a package of spending cuts, tax increases and privatisations agreed as part of a massive bail-out aimed at averting the euro zone's first default.
Following weeks of protests and rolling strikes, ADEDY, the public sector union representing half a million civil servants, and GSEE, which represents 2 million private sector workers, are stepping up pressure on deputies before the votes.
As thousands rallied in Syntagma square near the parliament, hundreds of hooded youths threw stones and bottles at police who responded with tear gas as the initially peaceful mood turned violent. A street umbrella was set fire outside a record-and-book store sending black smoke spiralling into the air above Syntagma Square near the parliament.
The protesters had marched through the capital chanting slogans, banging drums and carrying banners attacking the bail-out deal which many Greeks feel imposes harsh and unjust penalties on ordinary pensioners and workers while sparing the wealthy.
Transport and public services were hit, schools were shut and many shops and businesses were closed, while the streets of central Athens were virtually deserted. » | Tuesday, June 28, 2011
Verbunden »
THE DAILY TELEGRAPH: The US military spends about $20 billion (£12.5 billion) a year just to air-condition its bases in Iraq and Afghanistan, a retired senior officer has claimed.
Brigadier General Steve Anderson, who served as chief logistician to General David Petraeus in Iraq, said that the American department of defence (DOD) was shockingly inefficient in its energy use.
"In essence what we're doing is we're air conditioning the desert over there in Afghanistan, Iraq and other places," Brig. Gen. Anderson said.
Taking into account raw fuel, transport and security, "DOD will spend about $20 billion annually to air-condition tents and temporary structures," he told National Public Radio. » | Jon Swaine, New York | Tuesday, June 28, 2011
June 27, 2011

Gina Rinehart, 57, is the richest person in Australia and predicted to become the wealthiest in the world.
Her fortune has more than doubled to A$10.3 billion (£6.8 billion) in the past year because of a commodities boom.
She is on course to overtake Carlos Slim, the Mexican magnate worth £46 billion, and the Microsoft chairman Bill Gates, who is worth £35 billion, Citigroup has estimated.
The financial group calculates that three coal and iron ore projects she is developing will lead her to overtake the men mainly because she owns her companies outright and has no shareholders. » | Telegraph’s Foreign Staff | Monday, June 27, 2011
TELEGRAPH – BLOGS – ANDREW LILICO: Unless something odd happens, this week is likely to see an interesting but under-announced milestone: falls in house prices, in real terms, from their 2007 peak, exceeding 30 per cent (on the well-known Halifax measure). In cash terms, house prices peaked in August 2007, and fell 22 per cent to March 2009. After picking up a little in the second half of 2009 and early 2010, they went back to falling from mid-2010, and have been broadly flat during 2011.
But because inflation is high, that flat performance in cash terms for housing in 2011 means that, after adjusting for inflation, house prices have been falling apace. In real terms, since January 2010, house prices have fallen a further 12 per cent. » | Andrew Lilico | Monday, June 27, 2011

BBC: Is America in denial about the extent of its financial problems, and therefore incapable of dealing with the gravest crisis the country has ever faced?
This is a story of debt, delusion and - potentially - disaster. For America and, if you happen to think that American influence is broadly a good thing, for the world.
The debt and the delusion are both all-American: $14 trillion (£8.75tn) of debt has been amassed and there is no cogent plan to reduce it.
The figure is impossible to comprehend: easier to focus on the fact that it grows at $40,000 (£25,000) a second. Getting out of Afghanistan will help but actually only at the margins. The problem is much bigger than any one area of expenditure.
The economist Jeffrey Sachs, director of Columbia University's Earth Institute, is no rabid fiscal conservative but on the debt he is a hawk:
"I'm worried. The debt is large. It should be brought under control. The longer we wait, the longer we suffer this kind of paralysis; the more America boxes itself into a corner and the more America's constructive leadership in the world diminishes."
The author and economist Diane Coyle agrees. And she makes the rather alarming point that the acknowledged deficit is not the whole story.
The current $14tn debt is bad enough, she argues, but the future commitments to the baby boomers, commitments for health care and for pensions, suggest that the debt burden is part of the fabric of society:
"You have promises implicit in the structure of welfare states and aging populations that mean there is an unacknowledged debt that will have to be paid for by future taxpayers, and that could double the published figures."
Richard Haass of the Council on Foreign Relations acknowledges that this structural commitment to future debt is not unique to the United States. All advanced democracies have more or less the same problem, he says, "but in the case of the States the figures are absolutely enormous". » | Justin Webb, BBC News | Monday, June 27, 2011
June 26, 2011

REUTERS: Global interest rates must rise to avoid high inflation becoming entrenched, the Bank for International Settlements said on Sunday.
It also warned that delaying deficit cuts could risk intensifying the sovereign debt crisis and have grave consequences were investors to lose confidence in a major economy such as the United States.
"With the arrival of sharper price increases for food, energy and other commodities, inflation has become a global concern," the BIS said in its annual report.
"Tighter global monetary policy is needed in order to contain inflation pressures and ward off financial stability risks."
Of the four major central banks, the European Central Bank is the only one which has raised rates since the intensification of the financial crisis in late 2008. » | Sakari Suoninen | BASEL, Switzerland | Sunday, June 26, 2011

Norbert Schwaiger is a true veteran of EU summits. Now in his early 70s, the amiable German recalls with relish the triumphs and disasters from 34 years of service in Brussels as if they all happened yesterday. He chats about Delors, Kohl, Mitterrand, Chirac, Thatcher and the great rows with the British over money. The epic moments of European construction, from the Single European Act in 1986 to the Maastricht treaty in 1992 and the birth of the euro in 1999, are all fresh in his mind.
To catch up with Europe's progress, Schwaiger, a former press officer who retired in 2003, returned to a Brussels summit last week to take the temperature. Much had changed. "The historical idea has faded," he said wistfully. "When we started it was about Germany and France and the Benelux countries building a new Europe to stop the endless wars. Germany, and that generation of Germans, was ashamed of Hitler. It was about creating security, a secure Europe and a secure economy. Then they wanted to have Europe as their new home country."
As EU officials from 27 countries milled around the giant Justus Lipsius building, the venue of a summit dominated by the dire economic plight of Greece and the resulting existential threat to the euro and the EU itself, the contrast in mood could not have been starker from the heyday of integration that Schwaiger had known.
The talk was no longer of high ideals and "more Europe", but of mere survival for the European project. Where they used to talk of "ever closer union" in the commission press conferences, the phrase is now rarely, if ever, heard except when referring to history. José Manuel Barroso, the pragmatic European commission president, set his sights at this summit on "stability" for the foreseeable future, meaning the EU will do well to steady the ship in the face of Greece's financial implosion and possible exit from the single currency. Never mind any new European dreams.
From Schwaiger's perspective, one of the reasons why Europe has run out of idealism is the passage of time. He argues that Germany's postwar guilt, which did so much to power the European project, no longer drives young Germans to think about the EU as their parents and grandparents did. "In Germany the new generation, just out of school, has no memory of this," he says. Instead the young see a Germany united from its former east and west, communism fallen and a continent no longer haunted by its past or racked by the fear that it could plunge back into war. Much of Europe's original raison d'être has disappeared and Germany is now less willing to be its unquestioning, selfless paymaster. » | Toby Helm | Saturday, June 25, 2011
Subscribe to:
Posts (Atom)