Showing posts with label mounting debt. Show all posts

February 02, 2012

Bundesbank Sinks Deeper into Debt Saving Europe

THE DAILY TELEGRAPH: Germany's Bundesbank has entirely exhausted its stock of private assets and run up a quarter of a trillion euros in liabilities propping up the eurozone system, testing the political limits of EMU solidarity in Germany.

The operations are part of the European Central Bank's 'TARGET2' network of automatic payments between the national central banks of the Euroland club. The Bundesbank has already provided €496bn (£413bn) to countries in trouble, chiefly Greece, Ireland, Italy and Spain.

"This is reaching the danger point. It is already one and a half times the total budget of the German government," said Professor Frank Westermann of Osnabrück University. "If any of the crisis countries exits the euro or if there is an EMU break-up, the Bundesbank bears extreme risks."

The Bundesbank - the dominant body in the euro system - used to keep a stock of €270bn of private securities (refinance credit) before the start of the financial crisis. This was depleted last year as it sold assets to meet growing demands on the TARGET2 scheme.

Once the debt drama began to engulf the bigger economies, the Bundesbank was forced to borrow money to meet its obligations to offset capital flight, since it refused to sell its stash of gold. It now owes €228bn to German banks. Read on and comment » | Ambrose Evans-Pritchard, International Business Editor | Wednesday, February 01, 2012

July 14, 2010

Britain’s Debt: The Untold Story

THE INDEPENDENT: The true scale of Britain's national indebtedness was laid bare by the Office for National Statistics yesterday: almost £4 trillion, or £4,000bn, about four times higher than previously acknowledged.

It quantifies the burden that will be placed on future generations, and it is the ONS's first attempt to draw together the "off-balance-sheet" liabilities that have been accumulated by the state. The figures imply a huge "intergenerational transfer" – broadly in favour of today's "baby boomer" generation at the expense of younger people and future generations.

The debt primarily consists of the cost of public sector and state pensions, and of payments promised to private contractors under private finance initiatives. It far exceeds any of the figures so far published for the national debt, the largest current estimate for which is £903bn. That is projected to rise to £1.3trn by 2015.

If the current generation of taxpayers wanted to remove the higher bills facing their children and grandchildren, they would now be paying around 30 per cent more in tax. >>> Sean O'Grady, Economics Editor | Wednesday, July 14, 2010

June 07, 2010

Americans Like to Supersize Everything. Now They’ve Got Supersized Debt

MAIL ONLINE: America's $13trillion debt is set to overtake the country's GDP within the next two years as economists warn of a 'debt super cycle.'

Forecasters predict the U.S. debt will grow to surpass gross domestic product in 2012, based on data from the International Monetary Fund.

According to Bloomberg, the world's largest economy will expand at a slower pace than the 3.2 per cent average of the past five decades.

It comes as Barack Obama borrows record amounts to fund spending programs to help the economy recover from its longest recession since the 1930s.

'Over the long term, interest rates on government debt will likely have to rise to attract investors,' said Hiroki Shimazu, a market economist in Tokyo at Nikko Cordial Securities Inc.

'That will be a big burden on the government and the people.'

The forecast prompted warnings the country will be plunged into a debt 'super cycle' - which occurs when a debt exceeds the value of a nation's annual economic output. U.S. facing debt 'super cycle': $13trillion black hole to overtake country's GDP 'within two years' >>> Mail Foreign Service | Monday, June 07, 2010

Obamonomics©: A Definition >>> Mark Alexander | Saturday, March 07, 2009

April 29, 2010

Edmund Conway – Greek Crisis: Athens to Ashes

THE TELEGRAPH: The Greek horror story should scare us all, says Edmund Conway. Its problems are not unique.

Photobucket
Anger bubbles over in Athens Photo: The Telegraph

It has all the ingredients for a perfect Hollywood sequel. The cliffhanger plot kicks off right where its predecessor ended; the cast is stellar, some characters from the original reprising their roles. But this time the stakes are even higher, the mood even tenser.

Greece is on the brink of bankruptcy. Based on almost any yardstick, markets are now betting that the government will default on its debt. At a staggering 18 per cent, the going rate to borrow for a mere two years is similar to the penal rates credit card companies charge their dodgiest customers. The government, International Monetary Fund and European Union have promised, vaguely, to hand over the necessary cash to help tide the country over, but to no avail.

It would be all the more shocking had it not happened before. But Greece's problems today are merely Lehman Brothers redux. This is Global Meltdown 2. Granted, this time it is a country, rather than a mere bank, that faces collapse; this time, the victim may really be too big to fail. But the pattern is eerily familiar: the money starts to run out; investors realise with horror that there is a real chance of failure; the politicians promise that they will stand behind the institution; in a last-gasp attempt to halt the disaster, they ban short-selling; eventually the law of gravity proves irresistible, investors stage an effective run on the banks and the end is nigh.

Faced with such a scenario, there are two options: confront the crisis, knowing you simply may not have the firepower to deal with it, or go running, screaming, for the hills. The head of the Organisation for Economic Co-operation and Development, Angel Gurria, has chosen the latter path, declaring that the contagion is spreading "like Ebola... when you realise you have it you have to cut your leg off in order to survive".

Before we lapse into amateur dramatics, however, let's establish the facts: the market for Greek government debt has effectively frozen, much as the money markets did worldwide in 2007 – the initial trigger point for the crisis. Its banking system, stacked high with those same government bonds, is effectively insolvent. The country had been due to return to investors on May 19 to raise money; if a bail-out cannot be agreed by then, Greece will have no option but to default. But even that deadline is increasingly academic: the country has fallen victim to a run, and as anyone who watched Northern Rock's demise knows, what follows is not usually pretty. How did it come to this? >>> Edmund Conway | Thursday, April 29, 2010
Warning for Britain as Financial Chaos Spreads to Spain

THE TELEGRAPH: Spain's economy was thrown into chaos on Thursday when its credit rating was cut, sharpening fears that Britain may suffer a similar fate.

The turmoil came just a day after Greece’s rating was cut, increasing concerns of a Europe-wide financial crisis.

The euro fell sharply and the interest rates European governments pay to borrow money jumped after Standard and Poor’s, a credit ratings agency, downgraded Spain.

Last night the government in Madrid appealed for calm, promising an “austerity programme” to cut spending.

But economists fear that events in Spain show that financial “contagion” is spreading from Greece, as investors are scared off investing in any European country with significant government deficits. >>> James Kirkup and Christopher Hope | Thursday, April 29, 2010

Britain Risks Greek-style Crisis, Warns Vince Cable

THE TELEGRAPH: Britain risks sliding into a Greek-style fiscal crisis unless the next government takes drastic action to cut borrowing, warned Vince Cable, the Liberal Democrat finance spokesman.

Greece is currently in talks with the IMF and the European Union on getting a €45bn bail-out package to prevent a sovereign default, and a slashing of its debt to junk status has sent global financial markets into a tailspin.

"The Greek position is much more serious but is a salutary warning that unless the next government gets seriously to grips with the deficit problems, as we're determined to do, we could have a serious problem," Mr Cable told Reuters Insider television. >>> | Wednesday, April 28, 2010

April 28, 2010

Greek Debt Crisis Spreading 'Like Ebola' and Europe Must Act Now, OECD Warns

THE TELEGRAPH: The Greek debt crisis is spreading “like Ebola” and Europe must act now to protect the stability [of] the financial markets, according to the Organisation for Economic Co-operation and Development.
Photobucket
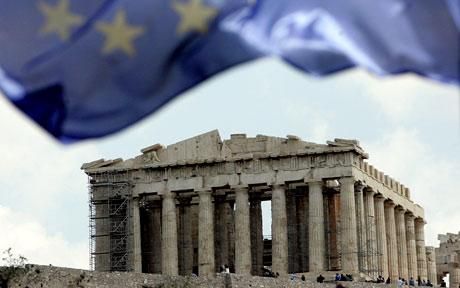
The Parthenon, Greece. Photograph: The Telegraph

“It’s not a question of the danger of contagion; contagion has already happened,” OECD secretary general Angel Gurria said.

“This is like Ebola. When you realise you have it you have to cut your leg off in order to survive,” he added, saying the crisis is "threatening the stability of the financial system".

Alistair Darling, the Chancellor, called for Eurozone countries to "urgently" agree a bail-out for Greece or risk a further decline in stock market confidence.

Mr Darling said it was "absolutely essential" that Greece's problems were sorted out "quickly, effectively and decisively", following a torrid 24 hours for world markets.

Asked on LBC Radio about the drop in the FTSE on Tuesday, the Chancellor said stock markets rise and fall but added: "That's my argument about the situation in Greece – we have got to make sure that it gets sorted out.

"But the primary responsibilities are for the other members of the euro group.

"They know that they have got to sort it out. They have promised money, and what I would say is they need to make that money available as soon as possible."

He added: "If we can sort out the problems in Greece quickly, then that will make people more confident."

The crisis in Greece sent stock markets and the euro reeling for a second day as fears grew that it would not be able pay its debts. >>> | Wednesday, April 28, 2010

ECB May Have to Turn to 'Nuclear Option' to Prevent Southern European Debt Collapse

THE TELEGRAPH: The European Central Bank may soon have to invoke emergency powers to prevent the disintegration of southern European bond markets, with ominous signs of investor flight from Spain and Italy.

Greece’s fortunes were dealt yet another blow as Standard & Poor’s slashed its credit rating to junk status - BB+ - the first time that has happened to a euro member since the single currency was created, pushing yields on 10-year Greek bonds up to a record 9.73pc.

The credit-rating agency also cut Portugal’s sovereign debt ratings by two notches to A-, as the swirling storm hit the country with full-force.

“We have gone past the point of no return,” said Jacques Cailloux, chief Europe economist at the Royal Bank of Scotland.“There is a complete loss of confidence. The bond markets are in disintegration and it is getting worse every day.

“The ECB has been side-lined in the Greek crisis so far but do you allow a bond crash in your region if you are the lender-of-last resort? They may have to act as contagion spreads to larger countries such as Italy. We started to see the first glimpse of that today.”

Mr Cailloux said the ECB should resort to its “nuclear option” of intervening directly in the markets to purchase government bonds.

This is prohibited in normal times under the EU Treaties but the bank can buy a wide range of assets under its “structural operations” mandate in times of systemic crisis, theoretically in unlimited quantities. >>> Ambrose Evans-Pritchard, International Business Editor | Tuesday, April 27, 2010
Crisis Spreads in Europe: Debt Downgrades in Portugal, Greece Sow Fear of Contagion; World Markets Hit

THE WALL STREET JOURNAL: Europe's hopes of containing Greece's credit crisis dimmed as the country's debt woes spread to Portugal, sparking a selloff in markets across the globe and testing the European Union's ability to protect its common currency.

The euro tumbled to its lowest point in a year against the dollar after Standard & Poor's Ratings Services cut Portugal's credit rating two notches and downgraded Greece's debt to "junk" territory, a first for a euro-zone member. The move is bound to worsen Greece's already dire fiscal situation and hamper a recovery. The news sent the bond yields in both countries soaring, a sign of distress.

The Dow Jones Industrial Average fell 213.04 points, or 1.9%, to 10991.99, suffering its worst decline in both point and percentage terms since Feb. 4. The pan-European Stoxx Europe 600 index tumbled 3.1%. As investors opted for the safety of bonds, the yield on Germany's 10-year benchmark was pushed down to 2.99%, moving below 3% for the first time in more than a year. Yields on U.S. Treasurys also dropped as investors bought.

Asian stock markets tumbled in early trading Wednesday on renewed worries about Greece's problems, with Japan's Nikkei 225 stock average shedding 2.8%.

The force of the market reaction to the downgrades suggests that the EU's fraught, months-long effort to stem Greece's debt crisis has all but failed. Portugal's stagnant economy has been viewed as among the weakest in the euro zone, although its deficit and debt levels aren't as high as Greece's. The debt rating downgrade on Tuesday, to A-minus from A-plus, fueled concerns that Portugal is on the same trajectory as its southern neighbor, despite its more solid fiscal position.

Greece's own turmoil was triggered in part by a similar ratings downgrade in December amid growing concerns about its debt. >>> Matthew Karnitschnig, Stephen Fidler and Tom Lauricella | Tuesday, April 27, 2010


TIMES ONLINE: ‘Greece infection’ spreads as stricken nation’s debt is rated junk: Greece plunged deeper into financial turmoil last night after its government bonds were rated as junk by financial markets. The Portuguese government debt also took a hammering after panic spread that a Mediterranean virus of insolvency and bad debts would infect the rest of Europe. >>> Carl Mortished and David Wighton | Wednesday, April 28, 2010

THE TELEGRAPH: Greece acts to stop speculators as debt crisis escalates: Greece has moved to stem panic in the country and stop speculators taking advantage of its escalating debt crisis. >>> Malcolm Moore in Shanghai | Wednesday, April 28, 2010

April 12, 2010

Euro Rallies On €30 Billion Greek Rescue

TIMES ONLINE: The euro surged to a one-month high and stock markets in Europe and Asia rallied today as traders welcomed a €30 billion (£26.5 billion) loans package for Greece, agreed by the currency's member countries to help the country tackle its debt crisis.

The euro surged to $1.3691 against the dollar, its highest level since mid-March, although concerns about the long-term nature of Greece's debt burden and worries about how the loans package would be implemented limited its gains.

The euro later dropped to $1.3574. Having fallen off sharply last week, it closed in New York on Friday at $1.3497.

"The euro is firmer as traders took heart from the Sunday announcement of the aid package for Greece,” said Daisuke Karakama, a currency analyst at Mizuho Corporate Bank. >>> Miles Costello, David Charter, Brussels | Monday, April 12, 2010

February 06, 2010

The Eurozone Faces Its Most Difficult Test Yet

THE INDEPENDENT – Leading Article: Policymakers must address the central problem of credibility

The European single currency has entered the stormiest seas it has yet experienced. Sovereign debt anxiety is swelling among global investors. There have been mounting fears over the soundness of Greek debt for several months. And this week those fears spread to encompass the borrowings of Spain and Portugal. Some suggest that the euro ship itself could capsize if this weather gets much worse.

It is important to recognise that, while several European nations have weak public finances, Greece has exceptional problems. Athens' budget deficit is abnormally large, as is its stock of debt. And the European Commission discovered recently that the Greek government had been engaged in dishonest accounting to disguise the scale of its liabilities. >>> | Saturday, February 06, 2010

November 29, 2009

Abu Dhabi Will Not Race to Dubai's Rescue

THE SUNDAY TELEGRAPH: Sheikh Mohammed of Dubai is under mounting pressure to explain the emirate’s debt problems, after Abu Dhabi indicated that it will not write a blank cheque to bail out its neighbour.

According to officials, Abu Dhabi, the richest state in the United Arab Emirates, will be cautious about how and whether to assist Dubai World, the state holding company that this week suspended repayments on a $3.5bn (£2.1bn) Islamic bond due in mid-December.

Any sign that Abu Dhabi’s support may not yet be secured could push global markets further into turmoil tomorrow, analysts said, especially if Dubai’s ruler maintains his silence on the crisis beyond this weekend’s Eid religious holiday. Sources said he may be forced to disrupt the 10-day Islamic break to make a statement as early as tomorrow.

“We will look at Dubai’s commitments and approach them on a case-by-case basis. It does not mean that Abu Dhabi will underwrite all of their debts,” a senior Abu Dhabi official said.

“Until things become clearer, it is very difficult to make any further investment decision on the bonds. Many things have to be clarified by Dubai.”

Dubai World’s $59bn of liabilities make up the majority of the emirate’s total $80bn debts. >>> Rowena Mason and Louise Armitstead | Sunday, November 29, 2009

August 17, 2009

Victor Davis Hanson: What Went Wrong

NATIONAL REVIEW ONLINE: Piling up debt, gaffes, and hypocrisy, Obama & Co. are sinking.

We are witnessing one of the more rapid turnabouts in recent American political history. President Obama’s popularity has plummeted to 50 percent and lower in some polls, while the public expresses even less confidence in the Democratic-led Congress and the direction of the country at large. Yet, just eight months ago, liberals were talking in Rovian style about a new generation to come of progressive politics — and the end of both the Republican party and the legacy of Reaganism itself. Barack Obama was to be the new FDR and his radical agenda an even better New Deal.


What happened, other than the usual hubris of the party in power?

First, voters had legitimate worries about health care, global warming, immigration, energy, and inefficient government. But it turns out that they are more anxious about the new radical remedies than the old nagging problems. They wanted federal support for wind and solar, but not at the expense of neglecting new sources of gas, oil, coal, and nuclear power. They were worried about high-cost health care, the uninsured, redundant procedures, and tort reform, but not ready for socialized medicine. They wanted better government, not bigger, DMV-style government. There is a growing realization that Obama enticed voters last summer with the flashy lure of discontent. But now that they are hooked, he is reeling them in to an entirely different — and, for many a frightening — agenda. Nothing is worse for a president than a growing belief among the public that it has been had.

Second, Americans were at first merely scared about the growing collective debt. But by June they became outraged that Obama has quadrupled the annual deficit in proposing all sorts of new federal programs at a time when most finally had acknowledged that the U.S. has lived beyond its means for years. They elected Obama, in part, out of anger at George W. Bush for multi-billion dollar shortfalls — and yet as a remedy for that red ink got Obama’s novel multi-trillion-dollar deficits.

Third, many voters really believed in the “no more red/blue state America” healing rhetoric. Instead, polls show they got the most polarizing president in recent history — both in his radical programs and in the manner in which he has demonized the opposition to ram them through without bipartisan support. “Punch back harder” has replaced “Yes, we can.” Fourth... >>> Vitor Davis Hanson | Monday, August 17, 2009